VAT returns in Belgium 2026
VAT returns in Belgium are filed by a foreign company that has an active BE VAT number and settles Belgian VAT on a monthly or – if the conditions are met – quarterly basis.
The guide explains deadlines, Intervat handling, payments, zero declarations, EC Sales List, Listing Clients, INTRASTAT, corrections and VAT excess refund.
Monthly or quarterly declaration?
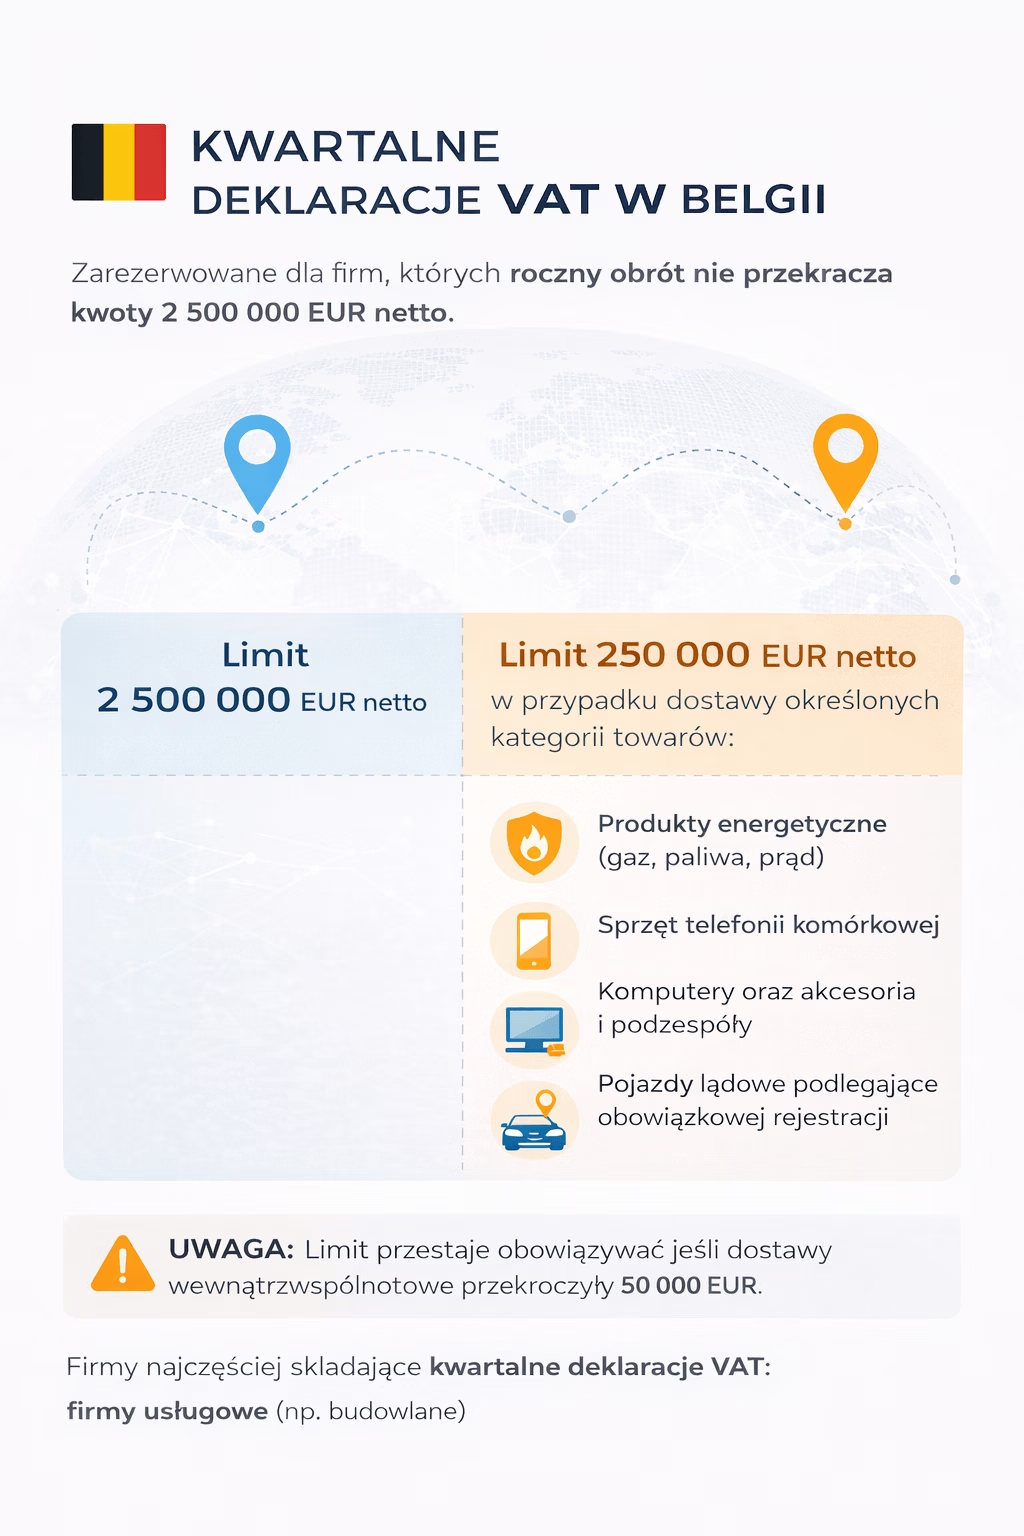
Monthly declaration is the general rule in Belgium. Quarterly settlement is only possible after all conditions are met—low turnover does not automatically qualify.
Monthly declaration
It is generally submitted by the 20th of the following month. The VAT resulting from the declaration must be paid by the same deadline.
Quarterly declaration
It can generally be submitted by the 25th day of the month following the quarter if the company meets the turnover limits and conditions for intra-Community returns.
Quarterly settlement terms
- the total net turnover does not exceed EUR 2,500,000;
- turnover in selected goods, including fuels, telephone equipment, computers and vehicles, does not exceed EUR 250,000;
- The company is not obliged to submit the EC Sales List monthly.
Declaration and payment deadlines
| Duty | Essential term | Important |
|---|---|---|
| Monthly declaration | 20th day of the following month | Payment has the same due date |
| Quarterly declaration | 25th day of the month following the quarter | Payment has the same due date |
| OSS Union / Non-Union | End of month after quarter | Separate declaration, payment and reference |
When setting specific dates for 2026, please always check the current FPS Finance calendar, including postponements of dates falling on public holidays.
Zero declarations
If a company is required to submit monthly or quarterly declarations, a lack of sales does not automatically mean a lack of declarations. During the period without sales, purchases and input VAT, intra-Community acquisitions (ICA), reverse charges, imports, adjustments, or transfers of own goods. Only after all items have been verified can a declaration be considered zero.
How does Intervat work?
Belgian periodic tax returns are filed electronically via Intervat. A foreign company may act through a person with appropriate access or through an authorized representative. Invoices are not required, but the data must comply with Belgian reporting categories.
Access and role
The user logs in using the appropriate identification method and selects a role authorizing them to act on behalf of the company.
Declaration data
Amounts can be entered manually or sent in a structured file from your accounting system.
Validation
Before sending, you must check the system messages, period, amount sign and the appropriate declaration fields.
Confirmation
After shipment, please keep the official receipt and make payment separately.
How to pay VAT in Belgium?
Submitting a declaration via Intervat does not automatically result in tax deduction. From May 1, 2026, periodic Belgian VAT payments must be made to the following account:
- IBAN
- BE41 6792 0036 4210
- BEAT
- GEBABEBB
The transfer must include the correct payment reference assigned to the obligation. An incorrect or missing reference may prevent the payment from being properly recorded.
EC Sales List, Listing Clients and INTRASTAT
Additional reports are separate obligations. They are not part of the periodic declaration or the VAT payment form.
EC Sales List
The EC Sales List includes relevant intra-Community supply chain transactions, B2B services reported in the summary information, and triangular transactions. The EC Sales List frequency may exclude quarterly VAT settlement.
Important: the correction of the EC Sales List is submitted according to the rules specific to this report, regardless of the correction of the periodic declaration.
Listing Clients
The Annual Customer Listing primarily covers sales to Belgian VAT payers. Foreign EU customers are not included in this list; the appropriate report for them is the intra-Community statement.
Simply having a BE VAT number doesn't mean a company has any items to report. If there are no relevant Belgian customers, a zero-entry list may occur; in certain cases, this is reported by checking the appropriate box on the periodic declaration.
INTRASTAT
The thresholds are assessed separately: imports into Belgium from other EU countries – €1,500,000; exports from Belgium to other EU countries – €1,000,000.
Intrastat in Belgium is a monthly report, submitted by OneGate by the 20th calendar day of the following month. The obligation begins the month after the threshold is exceeded. After reporting begins, nil declarations are also submitted for months without any flows.
How to correct your VAT return in Belgium?
The method for correcting an error depends on when it was discovered and the type of report. A single correction procedure should not apply to all responsibilities.
Before the statutory deadline
A periodic return may be replaced with a corrected version up to the statutory filing deadline. A receipt for the latest correct version must be retained.
After the statutory deadline
If a material error is discovered after the deadline, it must generally be included in the next periodic declaration, with explanatory documentation.
No declaration
Failure to submit a declaration may trigger administrative proceedings, liability assessments, and sanctions. It's not worth waiting for further notices to respond.
In practice, the operational impact of the VAT Chain reform primarily includes updated deadlines, restrictions on late declaration replacement, consequences for failure to submit a declaration, a current payment account, and refund conditions. These are not elements of a single, identical procedure for every report. The rules for documenting goods returns in Belgium and related corrections are described in a separate article.
Consequences of delays in VAT settlement
Late filing and late payment are separate violations. Failure to respond may result in increased penalties, interest, and administrative assessment of the liability.
No declaration
The administration may initiate a VAT substitution procedure and impose progressive penalties. Filing a missing return should not be postponed.
Late payment
Submitting the form on time is not sufficient if the VAT has not been paid separately to the correct account with the correct reference.
No additional report
EC Sales List, Listing Clients, and INTRASTAT are subject to their own deadlines and sanctions. Filing a periodic declaration does not replace these reports.
Active BE VAT number
Before you can start settling your accounts, your company must have an active BE VAT number. The requirements, documents, and procedure for obtaining identification are described in a separate guide.
Refund of excess VAT from the declaration
The refund of excess VAT is not automatic. The taxpayer must indicate the refund request in the return, submit the return by the deadline, and have a current bank account registered with the Belgian authorities.
One threshold for each monthly and quarterly declaration.
A refund can be claimed after each month. It should be completed no later than the end of the second month following the declaration period.
Refunds can be requested after each quarter. The deadline for reimbursement is no later than the end of the third month following the end of the quarter.
- marking the refund request in the declaration;
- demonstrating at least EUR 50 in excess;
- submitting the declaration within the statutory deadline;
- timely submission of declarations for the six months preceding the refund period;
- providing the correct bank account at least one month before the planned return date.
The refund may be offset against tax arrears or other liabilities, seized, or retained during an audit, including if the taxpayer fails to respond to a request from the administration.

CEO Taxenlight
Would you like to outsource VAT settlement in Belgium?
We will take over current VAT declarations, EC Sales List, Listing Clients, payments, corrections and contact with the Belgian authorities.
The most important rules for settling VAT in Belgium
One month is the rule
Quarterly requirement to meet turnover limits and EC Sales List frequency requirement.
Shipping and payment are separate
The declaration is sent via Intervat and the VAT is paid to the current account with the correct reference.
Reports have their own deadlines
EC Sales List, Listing Clients and INTRASTAT are not part of the periodic VAT return.
Corrections depend on the form
Before the deadline, the periodic declaration may be replaced; after the deadline, a material error is generally recognised in the following period.
Failure to sell does not end the obligation
You need to check, among other things, purchases, ITC, imports, reverse charges, corrections and movements of your own goods.
Return requires conditions
What counts is the right threshold, timely declaration, marked request and current bank account.
VAT Guides in Belgium
Select the topic of your transaction: import, warehouse, sales, invoices or billing.
Import and identification
Warehouse and e-commerce
B2B and foreign transactions
Invoicing and reporting
Billing and Compliance
Belgian VAT Returns 2026 - Frequently Asked Questions
Are VAT returns in Belgium filed monthly or quarterly?
Monthly settlement is the rule. Quarterly settlement is possible after meeting the €2,500,000 limit, the €250,000 limit for selected goods, and the EC Sales List frequency requirement.
What are the deadlines for VAT declaration and payment?
Monthly declarations and payments are generally submitted by the 20th of the following month, and quarterly declarations by the 25th of the month following the quarter. Specific dates must be confirmed in the FPS Finance calendar.
How does Intervat work?
Intervat is used to electronically submit declarations and reports. Confirmation must be retained after submission. The system does not automatically collect VAT; payment is made separately.
Is it necessary to submit nil declarations?
Yes, if the company is required to submit periodic declarations. The lack of sales does not preclude purchases, intra-Community acquisitions, reverse charges, imports, adjustments, or movements of own goods.
What is EC Sales List?
This separate report covers relevant IDT, B2B services, and triangular transactions. Its monthly frequency may exclude quarterly VAT settlements.
When is Listing Clients submitted?
The Annual Customer Listing primarily applies to sales to Belgian VAT payers. Customers from other EU countries are reported in the relevant intra-Community statement, not in the Client Listing.
What are the INTRASTAT thresholds in Belgium?
The threshold for imports from other EU countries is EUR 1,500,000, and for exports to other EU countries EUR 1,000,000. Each destination is assessed separately.
How to correct your Belgian VAT return?
A corrected return can be submitted by the statutory deadline, replacing the previous one. A material error discovered after the deadline is generally included in the next return. Additional reports are corrected separately.
How to pay VAT in Belgium?
From 1 May 2026, periodic VAT payments must be made to IBAN BE41 6792 0036 4210, BIC GEBABEBB, with the correct payment reference. Sending the declaration via Intervat does not result in a transfer.
When can I get a VAT refund?
A refund requires a request, a timely declaration, and a current invoice. For quarterly declarations, the threshold is €400 in Q1-Q3 and €50 in Q4; separate monthly refund systems may apply a threshold of €50.